
Storm damage insurance claims may involve several parts of a property and more than one cause of loss. Century Public Adjusters helps organize the evidence and communicate the documented repair scope to the insurer.
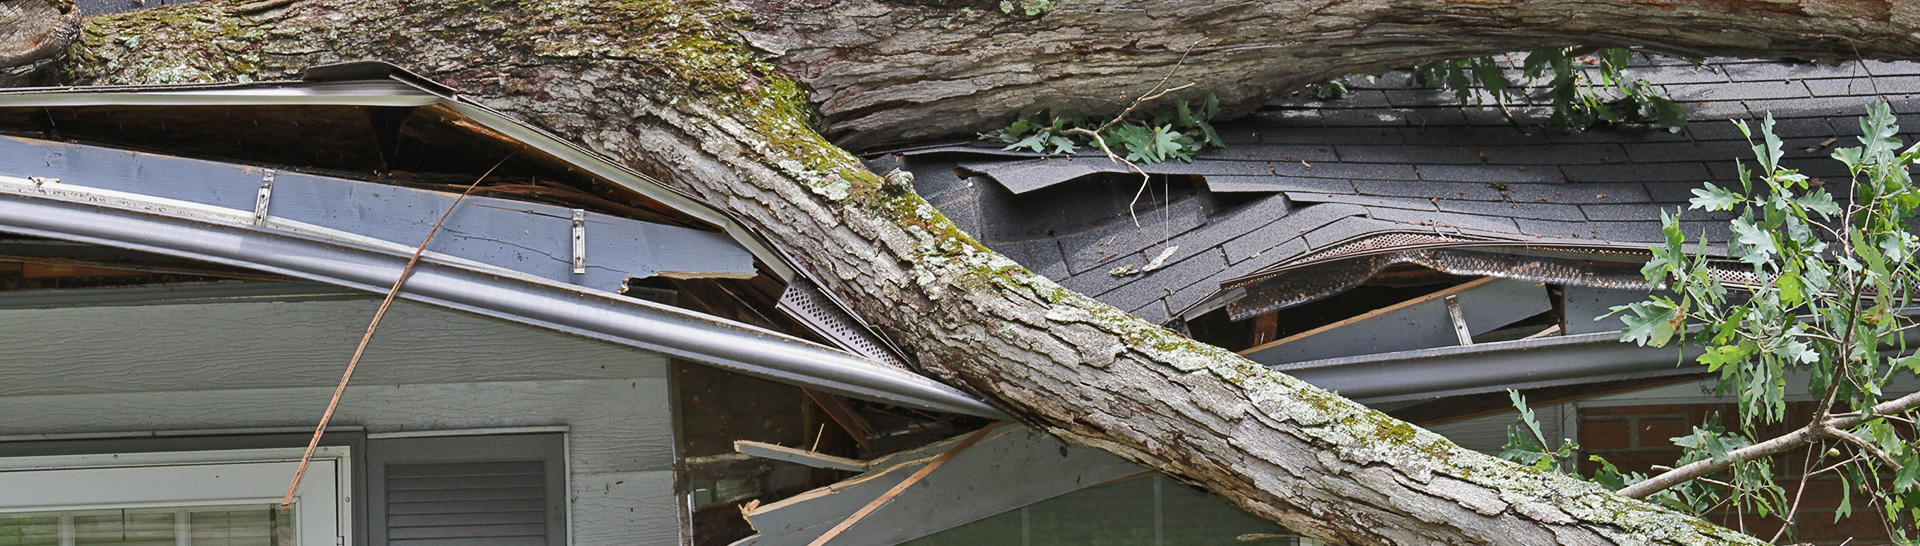
Ceiling stains, wet flooring and damaged roof areas need clear documentation. When safe, photograph what changed and keep temporary repair receipts. Our Florida rain and flood damage checklist explains what to gather before a claim review and why rising floodwater can involve a different policy from other storm damage.
Preparing records helps explain your claim, but it does not ensure reimbursement or priority treatment. Coverage, payment and timing depend on the policy and circumstances. Flood damage may require a separate policy.
We review new claims and existing insurer estimates or denials. Tell us your city, damage type and claim status. For related information, see our hurricane claim service and roof damage guidance.
We serve property owners throughout Florida, with dedicated support in Miami-Dade, Broward and Palm Beach, plus Tampa, Orlando, Fort Myers and Pensacola.
Call (888) 585-8010 or request a free property inspection. We explain our services and fees in writing before you decide to hire us.
First, make a simple list of the rooms or exterior areas affected. For each area, note what changed after the storm. Then match the photos and estimates to those locations. This helps avoid mixing damage from different parts of the property.
Also keep records of temporary repairs and any work already completed. For example, save the invoice and photos for a damaged window repair. If more damage becomes visible later, record when you noticed it. Give your insurer accurate information rather than guessing about the cause.
Finally, keep copies of each estimate and decision letter. Our team can compare those records with your observations and explain how Century may help with the claim.
Let’s start your claim today!
Get help organizing damage photos, estimates and claim documents. Our team can explain the claims process and discuss your property loss.
Bring us the denial letter, policy and supporting documents. We can review the stated reasons and discuss whether further review may be available.
If an estimate appears incomplete, we can compare the documented damage with the insurer’s assessment and discuss possible next steps.


